
Life is increasingly expensive. And for parents, this everyday financial strain can make saving money seem impossible.
“Many of the families we serve are doing their best to make ends meet and simply do not have extra income to set aside in a savings account,” says Tony Amezcua, director of the county-wide Bright Futures Educational Partnership. “Families frequently share that financial topics initially feel intimidating, especially when it comes to college costs, scholarships or savings programs.”
But a new college savings account for California’s kids, paired with a solid foundation in financial literacy, can help families plan for their children’s futures.
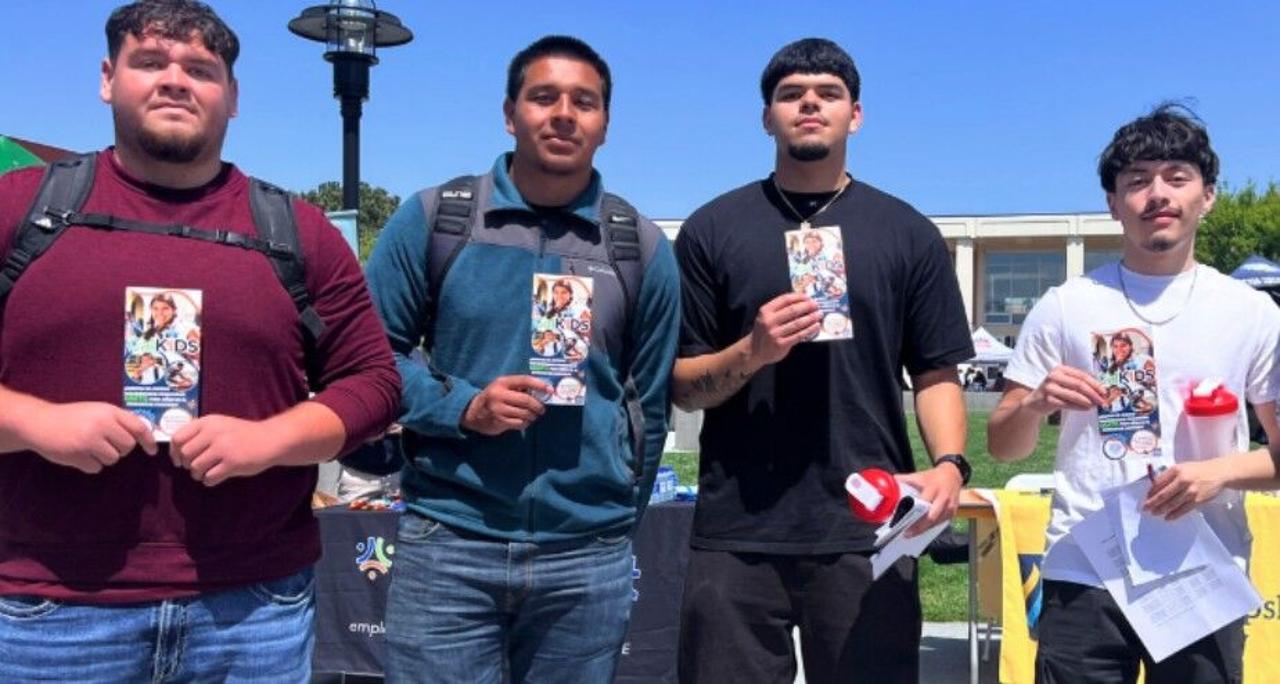
The CalKIDS scholarship, which was established and funded by the State of California in 2022, automatically awards money for college to all children born in California on or after July 1, 2022, and eligible public school students. These funds, held in a college savings account until the student is 17, are worth up to $1,500 for eligible public school students. Babies’ families can register newborns beginning at just 90 days old for their starting $100.
“CalKIDS is the easiest scholarship your child will ever receive,” Amezcua says. “There is no application, no interview or essays. This is money that already belongs to your child.”
This initiative launched in 2022 and is the nation’s largest children’s development account program for higher education with more than 5 million youth enrolled. CalKIDS has distributed $53 million to nearly 100,000 students as of June 2025.
CalKIDS scholarships are not limited to paying for tuition at a four-year institution. Testimonials on the CalKIDS website describe students using their scholarships to pay for books, parking fees or a certification program related to their area of study. CalKIDS funds are accepted at accredited educational institutions in the U.S., including community colleges, universities, vocational schools and professional schools.
“Don’t leave [the CalKIDS scholarship] unclaimed. It only takes three or four minutes. Do not miss out on this opportunity,” Amezcua says. “Taking a few minutes today can make a meaningful difference in their future.”
Alongside the cash infusion, CalKIDS representatives say it aims to “give every one of these students a reason to believe in their path to higher education.” One of CalKIDS’ core beliefs is, “a little hope can go a long way in realizing educational aspirations.”
Amezcua echoes this idea, explaining the CalKIDS scholarship can change a parent’s expectation for their child’s future from the beginning.
“When families learn funds already exist for their child’s education, college and career pathways feel real, possible and expected,” Amezcua says. “That early signal helps build belief, identity and aspiration. These conversations not only lead to participation but often open the door to deeper engagement around academic planning and long-term goals.”
Bright Futures Monterey County emphasizes financial literacy as part of its overall strategy to improve education, from encouraging families to claim CalKIDS accounts to helping them complete the FAFSA or understand the true cost of college.
“Financial literacy helps families make informed decisions with confidence,” Amezcua says. “Helping families access resources that already exist for them [breaks] cycles of limited information and limited access.”
Access to smart money advice is not exclusive to parents approaching their teen’s college decision, says Leinette Limtiaco, vice president of Central Coast branch operations for Wescom Financial, a credit union headquartered in Pasadena.
“I started teaching my own kids about saving and managing money from the time they were very young and I’ve learned that those early conversations really matter,” Limtiaco says. “Financial literacy isn’t one big lesson. It’s a series of small, everyday moments that build confidence over time.”
Limtiaco advises parents to consider the financial priorities they wish to teach their young children, whether that is the power of saving money or following a budget. Consider including your kids in goal-setting conversations, for instance if extra household funds should go toward saving toward a family vacation or a new car.
“Including them in those decisions teaches prioritization and delayed gratification in a very natural way,” Limtiaco says. “Small, ongoing discussions make finances feel normal and approachable. Ultimately, building solid money habits in your family is about creating regular, interactive moments where parents and kids learn together.”
Teens and young adults can be intrigued about advanced financial tools that can build assets, such as credit cards and investments. However, Limtiaco advises this age group to analyze their “day-to-day money” and cash flow as a first step, before researching investments that may align with their goals. Wescom offers an online Youth Financial Education Center with 25 free educational modules on topics from savings accounts and credit scores.
“Our guidance is usually to start with consistent saving habits and an emergency cushion,” Limtiaco says. “It sounds simple, but understanding those ‘banking basics’ is the foundation for everything else.”